26 Oct 7 Home Gym Equipment Financing Options for Any Credit Score
The best home gym equipment financing is the plan you can pay off inside its interest-free window. For most buyers with good credit, that means a 0% APR retailer plan or a 0% intro APR credit card. If the gear costs under roughly $1,000, a pay-in-4 plan is simpler. For bigger machines, or a score that won’t qualify for 0%, a fixed-rate personal loan or a monthly installment plan spreads the cost predictably. Lease-to-own is the last resort for bad or no credit, because it usually costs the most.
The problem is that good cardio equipment isn’t cheap. Commercial-grade machines at 3G Cardio run from about $1,500 to $4,250, and the financing menu is confusing. You will see 0% APR, deferred interest, buy now pay later, and rates from 0% to 36% APR. Pick the wrong plan and a $2,000 purchase can quietly become a $2,450 one.
This article ranks seven ways to pay for a home gym over time. Each one covers how it works, who it suits, and what it really costs. After the list, you get a side-by-side comparison, a worked $2,000 example, and answers on approval odds, HSA/FSA use, and tax credits. 3G Cardio sells its machines directly, so the first option is our own. The rest apply at most fitness retailers.
1. PayPal Credit 6-month 0% financing at 3G Cardio
This is the simplest option if you are buying a 3G Cardio machine and have good credit. It is a short, interest-free window with no separate loan application outside checkout.
How it works
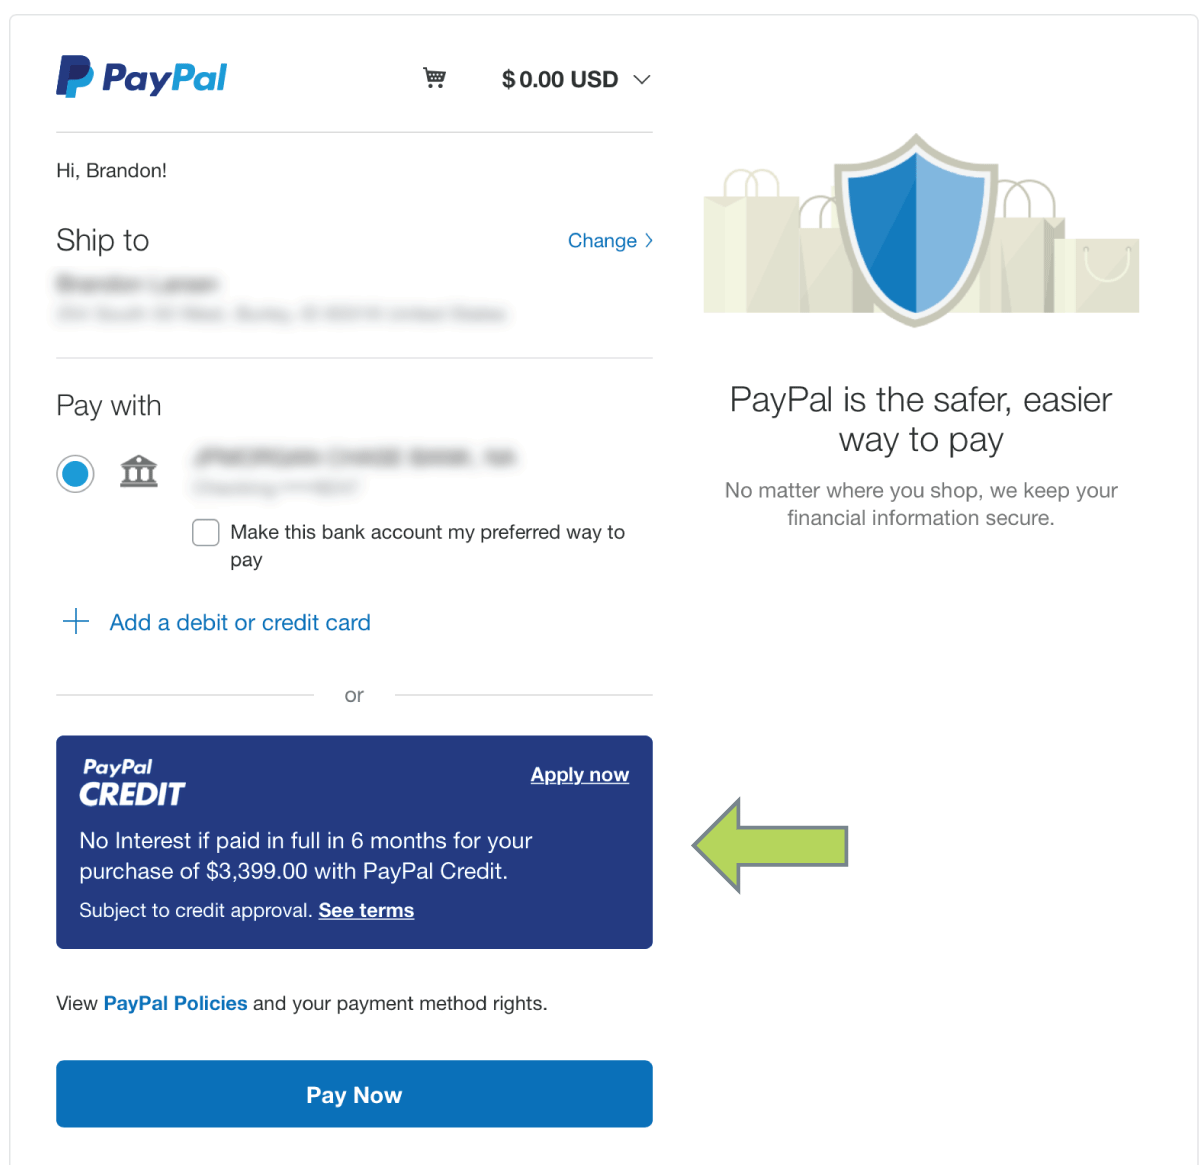
3G Cardio offers 6 months 0% financing through PayPal Credit. You choose PayPal at checkout, apply for PayPal Credit, and, if approved, the purchase goes on that account. Pay the full balance within six months and you owe no interest. With promotions like this, interest generally accrues from the purchase date and is added if any balance remains when the window closes. Read the offer terms before you accept.
The math is simple. Divide the price by six:
- $2,000 machine: $333.33 per month
- $4,000 machine: $666.67 per month
- Pay the balance off in month five and you still owe $0 in interest
A 0% window only works if you can afford the price divided by the number of months.
Who it suits and what it costs
This plan suits buyers with good credit and a clear payoff plan, such as a tax refund or a bonus coming within six months. On a flagship machine like the Elite Runner X Treadmill, the six-month payment is steep. If the monthly figure strains your budget, move to a longer option below.
Buying direct has one more advantage. 3G Cardio offers a full 30-day money back guarantee that also covers shipping costs. Before you finance, email Support@3GCardio.com and ask how a return would settle a PayPal Credit balance. Check each product page for current pricing.
2. Retailer store credit cards with 6 to 24 month promotions
Many fitness retailers partner with a card issuer such as Synchrony to offer longer 0% windows than a single six-month plan. The window usually grows with the size of the purchase.
How it works
One online fitness retailer’s program shows the typical structure. You apply at checkout or by phone, and the promotional length depends on your purchase total. Here are those tiers, with the monthly payment needed to clear a $1,500 order:
| Window | Minimum purchase | Monthly to clear $1,500 |
|---|---|---|
| 6 months | $199 | $250.00 |
| 12 months | $499 | $125.00 |
| 18 months | $699 | $83.33 |
| 24 months | Call for details | $62.50 |
The same program lists a fixed 9.9% APR for 24 or 36 months on purchases of $1,000 or more with its card. Those are one retailer’s terms, so check the current offer wherever you shop.
Deferred interest means a single unpaid dollar at the deadline can trigger back interest on the whole purchase.
Who it suits and what it costs
This option suits disciplined buyers with good credit who want lower monthly payments. The risk is that minimum monthly payments rarely clear the balance in time. The card’s required minimum is usually smaller than price divided by months.
Ignore the minimum and pay the full amount from the table. Set an automatic payment for that figure, and set a calendar reminder a month before the deadline. After the promotion ends, store card APRs are typically high, so the card is a tool for one purchase and not a long-term loan.
3. Pay in 4 interest-free biweekly payments
Pay in 4 splits a smaller purchase into four equal payments, usually every two weeks. It is the fastest way to ease the sting of a bench, rack, dumbbells, or an entry-level machine.
How it works
You pay the first quarter at checkout and the other three payments follow every two weeks. Retailer limits vary. One lists purchases from $30 to $1,500, and another from $50 to $999.99. Providers often advertise no interest and no late fees, and some say the plan does not affect your credit score. Confirm those terms in the provider’s agreement before you rely on them.
For an $800 purchase, you pay four times $200, and the whole plan wraps up in about six weeks.
Pay in 4 is a budgeting trick for small orders, not a way to finance a treadmill.
Who it suits and what it costs
This works for accessories, strength gear, and smaller purchases where you have the cash within weeks but want to smooth it out. It is also a decent fallback if your credit is thin, since approval standards are often lighter than for a store card.
It does not work for most cardio machines, which sit above the usual caps. If your cart total exceeds the limit, the option simply won’t appear at checkout. Missing a payment can bring fees at some providers, so treat the four dates like bills.
4. Monthly installment plans through Affirm, Bread Pay, and similar providers
Buy now, pay later providers also offer longer monthly installment loans. Terms and rates differ, and a good credit profile can mean 0% while a weaker one means a high APR.
How it works
You select the provider at checkout, answer a few questions, and see your exact terms before you commit. Minimums vary, such as $250 for one provider’s plans. One fitness brand lists plans of 3, 6, 12, 24, or 36 monthly payments, with rates from 0% APR for qualified customers up to 36% APR. Another advertises as low as 0% APR for up to 12 months through Affirm.
Here is what $2,000 looks like under two outcomes:
| Plan | Monthly payment | Interest paid |
|---|---|---|
| 0% APR, 12 months | $166.67 | $0 |
| 20% APR, 24 months | about $102 | roughly $445 |
The APR you are offered decides whether installment financing is free or costs 20% more.
Who it suits and what it costs
This suits buyers who want a fixed payment and a known end date with no revolving card balance. It is a strong choice for mid-range machines when a store card is not available or you prefer simple interest.
Look at the total repayment figure on the offer screen, not the monthly number. If you are quoted a rate near the top of the range, compare it against a personal loan or a 0% card before you click confirm. Most providers show your terms without a hard credit check, but verify this before applying.
5. A credit card with a 0% intro APR
A new card with a 0% introductory purchase APR is the cleanest interest-free option when you have good credit and want a long window.
How it works
Many cards offer 0% on purchases for a set number of months, often in the range of 12 to 21. You buy the machine on the card and pay it down each month. Unlike a deferred-interest promotion, interest on these cards generally starts only on the balance left after the intro period ends, not on the original purchase. Retail promos and cards are not the same product, so read the card agreement.
For a $2,000 purchase over a 15-month intro window, aim for $133.33 per month. 3G Cardio accepts Visa, MasterCard, Amex, and Discover, so you can use any of them at checkout.
Intro APR cards charge interest only on what you still owe after the window, which makes them safer than deferred-interest plans.
Who it suits and what it costs
This option suits buyers with good to excellent credit who can pass a full credit check and will be approved for a limit that covers the machine. A low limit is the most common snag, so confirm your limit before ordering.
Watch for two catches. Some issuers end the promotional rate after a late payment, and the regular APR that follows the intro period is usually high. Set autopay for the monthly target, and plan to clear the card before the intro window ends.
6. A fixed-rate personal loan
A personal loan gives you cash up front and a fixed payment for a fixed term. It works when you want to buy from any seller, compare prices freely, or need a longer runway than a promotion offers.
How it works
You borrow a set amount from a bank, credit union, or online lender and repay it in equal monthly installments. Terms commonly run from one to seven years, though the range varies by lender. Because you receive cash, you are not tied to one retailer’s checkout. That also means you can shop around, price match, or buy refurbished equipment.
Here is an illustration of $4,000 at 12% APR over 36 months. It is an example, not a quote:
- Payment: about $133 per month
- Total repaid: about $4,783
- Interest: about $783
A personal loan trades the 0% window for a lower-risk, predictable schedule.
Who it suits and what it costs
Personal loans suit buyers with fair to good credit who want predictable payments and don’t mind paying some interest. Interest starts on day one, and some lenders charge an origination fee, so compare the APR and not just the stated rate.
Ask for prequalification, which many lenders offer with a soft credit check. Check a credit union first, since members often get competitive rates. If your credit is rough, a cosigner can lower your rate, but they become responsible if you stop paying, so that is a serious ask.
7. Lease-to-own and no-credit-check plans
This is the option for buyers who can’t qualify elsewhere. It gets the equipment into your home quickly, but you pay for that convenience.
How it works
With lease-to-own, you make weekly or monthly payments for a set term, and you own the equipment at the end. Approval usually rests on your income and bank account rather than your credit score. Because the provider carries more risk, the total cost typically ends up well above the sticker price. Some plans include an early purchase window that cuts the cost sharply if you buy out the lease early.
Before you sign, find these numbers in the contract:
- The total of all payments over the full term
- The early buyout price and the deadline for it
- Late fees and what happens if you miss a payment
If a plan will not state its total cost clearly, treat that as a reason to walk away.
Who it suits and what it costs
This suits buyers with bad or no credit who need the equipment now and understand the premium. Before choosing it, test the cheaper paths first. You can save a down payment and use Pay in 4 for part of the order, choose a lower-priced model, or buy refurbished. A credit union loan with a cosigner is another option. Waiting two or three months to save can beat paying a lease premium for years.
How to choose and what to check before you sign
Match the plan to your credit and to how fast you can repay. Pick the shortest, cheapest plan whose monthly payment you can cover without strain.
Side-by-side comparison
This table puts all seven options together:
| Option | Typical window | Interest | Credit needed |
|---|---|---|---|
| PayPal Credit promo | 6 months | 0% if paid in time | Good |
| Store card promo | 6 to 24 months | 0% if paid in time | Good |
| Pay in 4 | About 6 weeks | Usually none | Light |
| Installment plan | 3 to 36 months | 0% to 36% APR | Fair to good |
| 0% intro card | Often 12 to 21 months | 0% on the balance during intro | Good to excellent |
| Personal loan | 1 to 7 years | Fixed APR | Fair to good |
| Lease-to-own | Varies | Built into total cost | Low or none |
For $2,000, the worst case is a high-APR plan over 24 months, about $445 in interest. A 12% personal loan over 36 months costs about $391 in interest, or roughly $66.43 per month. The best case is $0 interest on a 0% plan, as long as you pay on schedule.
Approval, HSA/FSA, and tax credits
How hard is approval? 0% promotions generally go to applicants with good credit, while installment loans and personal loans reach further down. Prequalify where you can, since a soft check does not hurt your score, and avoid stacking hard inquiries. If you are outfitting a commercial gym, equipment loans and leases are a different product with business requirements such as time in business and revenue.
Is there a tax credit? There is no general federal tax credit for buying home gym equipment. 3G Cardio machines can be bought with HSA/FSA funds, but whether your plan reimburses the purchase depends on your plan and usually on a doctor’s letter of medical necessity. Ask your plan administrator before you pay.
Picking a plan you can actually pay off
Home gym equipment financing comes down to one test: can you pay the full amount within the interest-free window, or can you afford the fixed payment on a loan you have priced honestly? Use a 0% plan when the answer is yes, pay in 4 for small orders, a loan or installment plan when you need more time, and lease-to-own only when nothing else will approve you.
If you are ready to look at a machine, compare 3G Cardio’s lineup, starting with the Elite Runner X Treadmill, and check the current price and the 6-month 0% PayPal Credit option at checkout.
No Comments